

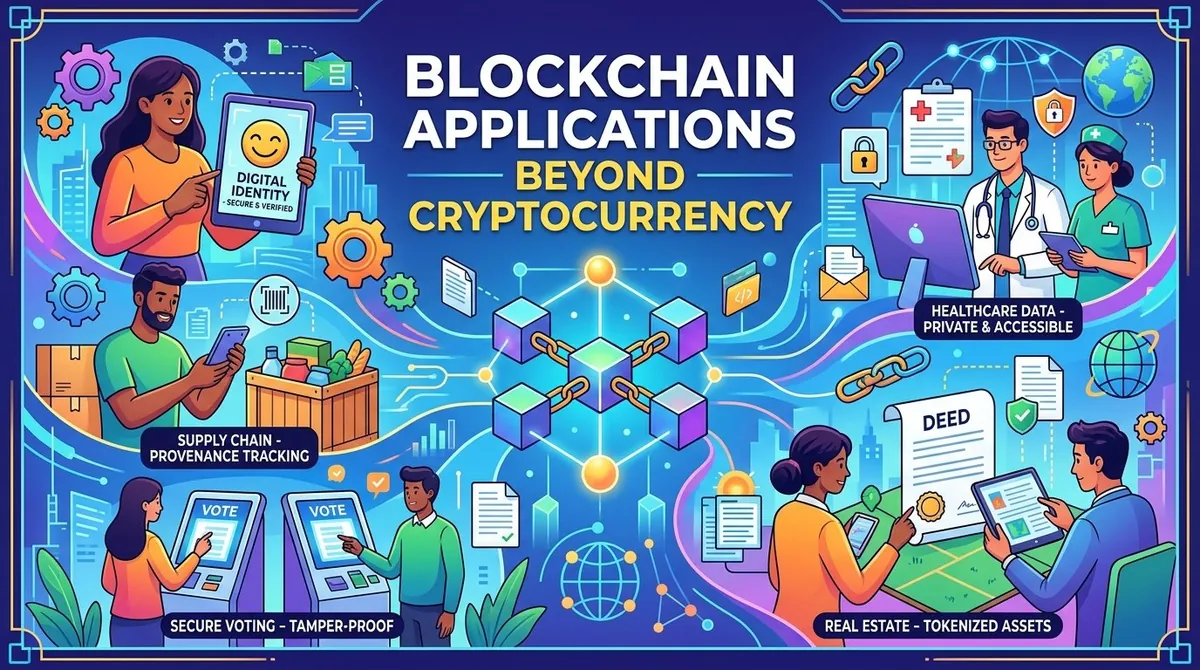
Blockchain technology is often associated with cryptocurrencies, but its underlying architecture has applications that extend beyond digital currencies. Businesses and organizations have explored blockchain for areas such as supply chain management, digital identity, recordkeeping, payments, and transaction verification.
The technology provides a way to maintain shared records across a distributed network, potentially reducing the need for centralized reconciliation in certain processes. Its practical value, however, depends on whether the characteristics of blockchain address a genuine business problem better than conventional technologies.
Understanding Blockchain Technology
A blockchain is a distributed digital ledger that records transactions or other information across a network. Records are grouped into blocks and linked together, creating a chronological chain of information.
Depending on the type of blockchain, participants can have different roles and permissions. Public blockchains generally allow broad participation, while permissioned blockchain networks can restrict access to approved organizations or users.
The important business concept is not cryptocurrency itself but the ability to maintain and verify shared records among multiple participants.
Supply Chain and Product Tracking
Supply chain management is one area where blockchain applications have received significant attention. Modern supply chains often involve manufacturers, suppliers, distributors, logistics companies, retailers, and customers.
When information is stored across separate systems, organizations may need to reconcile records between participants. A shared blockchain-based record can provide a common source of transaction information when the participating organizations agree on how the network should operate.
For example, businesses can use distributed records to document the movement of products through different stages of a supply chain. Combined with other technologies such as sensors and identification systems, blockchain can contribute to greater visibility into the history of physical goods.
Improving Recordkeeping and Verification
Businesses regularly exchange documents and records that need to be verified. Blockchain can provide a tamper-evident record of when information was added or a transaction occurred.
This can be useful in situations where multiple parties need access to a consistent history of events. Instead of each participant maintaining an independent record, a blockchain network can provide a shared ledger that authorized participants can reference.
However, blockchain does not automatically guarantee that the information originally entered into the system is accurate. Businesses still need reliable processes for collecting and validating information before it is recorded.
Digital Identity and Credentials
Blockchain technology has also been explored for digital identity and credential management. Organizations frequently need to verify information about customers, employees, suppliers, or professional qualifications.
Distributed systems can potentially support credentials that can be verified without requiring every organization to maintain an identical database. For example, digital credentials could allow individuals or organizations to demonstrate specific information to an authorized party.
Implementation requires careful attention to privacy, access controls, and regulatory requirements. Identity systems must balance verification with the protection of personal information.
Smart Contracts and Business Processes
Smart contracts are programs stored and executed on blockchain networks that can perform predefined actions when specified conditions are met.
Businesses can explore smart contracts for processes involving multiple parties and clearly defined rules. For example, a system could automatically record or initiate an action after certain conditions have been verified.
This can reduce manual steps in suitable workflows, but smart contracts are not a replacement for every conventional agreement or business process. Their usefulness depends on whether the underlying conditions can be clearly defined and reliably verified.
Building a Blockchain Strategy
Organizations considering blockchain should begin with the business problem rather than the technology. A blockchain network can introduce additional complexity, so its characteristics should provide a meaningful advantage over conventional databases or other systems.
A practical evaluation can include:
- Identify the participants: Determine whether several independent organizations need to share and verify the same information.
- Define the trust requirements: Establish why existing systems or intermediaries may not adequately address the problem.
- Evaluate the data: Determine what information should be recorded and how its accuracy will be established.
- Select the appropriate architecture: Consider whether a public, private, or permissioned network is appropriate.
- Measure the results: Compare costs, processing times, transparency, reconciliation requirements, and other relevant outcomes.
A focused pilot can help organizations determine whether blockchain provides sufficient value before larger investments are made.
Common Challenges of Blockchain Adoption
Blockchain projects can face technical, operational, and regulatory challenges. Integrating a distributed ledger with existing business systems may require significant development work, particularly when organizations use different data standards.
Governance is another important consideration. When multiple organizations participate in a network, they need agreements covering access, responsibilities, technical changes, and dispute resolution.
Scalability and performance can also vary between blockchain architectures. Businesses therefore need to evaluate transaction volumes, processing requirements, and network design before selecting a solution.
Blockchain and Business Transparency
One potential advantage of blockchain applications is increased visibility into shared transactions. When authorized participants can reference the same record, organizations may spend less time reconciling information across separate systems.
This can be particularly relevant in industries where transactions pass through multiple organizations. Greater transparency can help participants understand the history of an asset or transaction and identify discrepancies more efficiently.
At the same time, transparency does not mean that every piece of information should be publicly accessible. Businesses need to determine which participants should see particular records and implement appropriate privacy controls.
Measuring the Business Value
Blockchain initiatives should be evaluated against measurable business objectives rather than the novelty of the technology. Relevant indicators can include transaction processing time, reconciliation costs, administrative workload, record accuracy, or the time required to verify information.
Organizations should also consider the total cost of maintaining the blockchain network and integrating it with existing systems. A solution that improves one part of a process but creates significant complexity elsewhere may not deliver the expected overall benefit.
Clear measurement can help businesses determine whether a blockchain application should be expanded, redesigned, or replaced with another technology.
The Future of Blockchain Applications
Blockchain development is increasingly being considered as part of broader digital infrastructure rather than solely as a foundation for cryptocurrency. Its potential applications include supply chains, financial services, digital credentials, asset records, and business-to-business transactions.
The technology is unlikely to be necessary for every organization or process. In many situations, conventional databases and centralized systems may remain more appropriate.
The most practical approach is therefore to evaluate blockchain according to the specific requirements of a business process. Where multiple participants need a shared and verifiable record, blockchain may provide useful capabilities. Where those requirements do not exist, a simpler technology may be more suitable.
As businesses continue experimenting with distributed technologies, the focus is likely to remain on practical applications, interoperability, governance, and measurable business outcomes rather than cryptocurrency alone.